जमीन खरीदने वालों के साथ होने वाले सबसे बड़े धोखों में से एक है — गिरवी (बंधक) रखी जमीन बेच देना। विक्रेता ने उस जमीन पर बैंक से ऋण लिया होता है, मूल केवाला बैंक के पास जमा होता है, और खरीदार को इसकी जानकारी तब मिलती है जब बैंक वसूली का नोटिस भेजता है। अच्छी बात यह है कि बिहार में यह जाँच काफ़ी हद तक ऑनलाइन और मुफ़्त हो सकती है। इस गाइड में बंधक जाँचने के सभी तरीके दिए गए हैं।
बंधक (मॉर्गेज) का मतलब
जब कोई व्यक्ति जमीन को ज़मानत के रूप में रखकर बैंक या वित्तीय संस्था से ऋण लेता है, तो वह जमीन बंधक हो जाती है। ऋण चुकने तक बैंक का उस पर अधिकार (charge) रहता है। ऐसी जमीन खरीदने पर बैंक उसे नीलाम भी कर सकता है, इसलिए रजिस्ट्री से पहले जाँच ज़रूरी है।
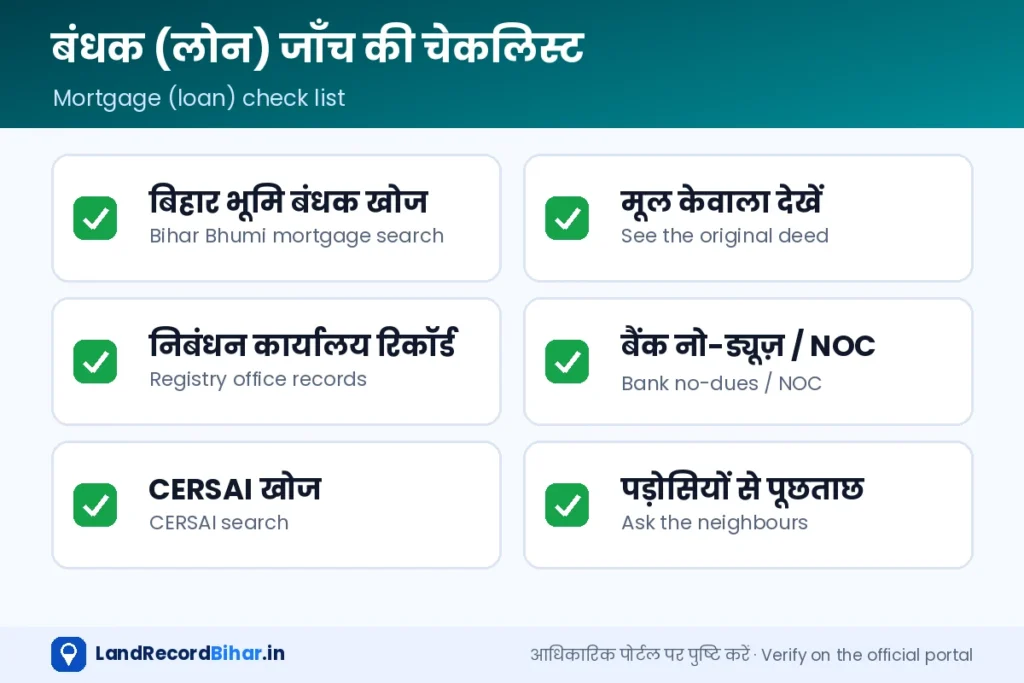
तरीका 1: बिहार भूमि पर बंधक भूमि की ऑनलाइन जाँच
- पेज खोलें: बिहार भूमि पोर्टल की “बंधक भूमि देखने की सुविधा” खोलें (नीचे बटन)।
- स्थान चुनें: ज़िला, अंचल और मौजा चुनें।
- खाता-खेसरा डालें: जिस जमीन को खरीदना है, उसका खाता और खेसरा दर्ज करें।
- परिणाम देखें: बंधक दर्ज हो तो बैंक/संस्था का नाम, तिथि और स्थिति दिखती है।
बंधक भूमि जाँचें ↗ डैशबोर्ड पर सेवा
हर बंधक इस सूची में दर्ज हो, यह ज़रूरी नहीं। इसलिए नीचे के बाकी तरीके भी अपनाएँ।
तरीका 2: मूल केवाला देखें
बैंक ऋण देते समय अक्सर मूल केवाला (टाइटल डीड) अपने पास रख लेता है। विक्रेता से मूल दस्तावेज़ दिखाने को कहें। अगर वह सिर्फ़ फ़ोटोकॉपी दिखाए या मूल “खो जाने” की बात करे, तो यह खतरे का संकेत है।
तरीका 3: निबंधन कार्यालय में भार (encumbrance) की जानकारी
पंजीकृत बंधक-पत्र (mortgage deed) निबंधन कार्यालय के रिकॉर्ड में रहते हैं। जिस कार्यालय में जमीन की रजिस्ट्री होती है, वहाँ से उस संपत्ति पर पिछले वर्षों के पंजीकृत दस्तावेज़ों की जानकारी ली जा सकती है। बड़े सौदों में यह जाँच किसी अधिवक्ता के माध्यम से कराएँ।
तरीका 4: बैंक का अनापत्ति/नो-ड्यूज़ प्रमाण पत्र
अगर विक्रेता मानता है कि पहले ऋण था पर चुका दिया गया, तो उससे बैंक का नो-ड्यूज़/अनापत्ति प्रमाण पत्र और बंधक मुक्त होने (release) का कागज़ लें। ज़रूरत हो तो बैंक शाखा से सीधे पुष्टि करें।
तरीका 5: केंद्रीय रजिस्ट्री (CERSAI) की खोज
बैंक और वित्तीय संस्थाएँ संपत्ति पर बनाए गए सुरक्षा हित (security interest) को केंद्रीय रजिस्ट्री CERSAI में दर्ज करती हैं। इसकी सार्वजनिक खोज सुविधा से भी संपत्ति पर बैंक के दावे का पता लगाया जा सकता है। ग्रामीण कृषि भूमि के लिए यह हमेशा कारगर न हो, पर शहरी प्लॉट/फ़्लैट में उपयोगी है।
खतरे के संकेत
- विक्रेता मूल कागज़ न दिखाए या जल्दबाज़ी करे।
- सौदे की कीमत बाज़ार से बहुत कम हो।
- जमाबंदी की टिप्पणी में किसी बैंक/ऋण का उल्लेख हो।
- पड़ोसी बताएँ कि जमीन पर लोन है या बैंक का नोटिस आया था।
बंधक के अलावा ये जाँच भी करें
बंधक जाँच के साथ जमाबंदी, खतियान, नक्शा, लंबित दाखिल-खारिज और न्यायालय वाद की जाँच भी ज़रूरी है — पूरी सूची हमारी जमीन खरीदने से पहले 10 जाँच गाइड में है।
अक्सर पूछे जाने वाले प्रश्न
किसान क्रेडिट कार्ड (KCC) ऋण वाली जमीन बेची जा सकती है?
KCC ऋण के लिए भी जमीन पर बैंक का charge बनाया जा सकता है। ऐसी जमीन बेचने से पहले ऋण चुकाकर बैंक से मुक्त होने का कागज़ लेना चाहिए।
अगर गिरवी जमीन खरीद ली तो?
तुरंत किसी अधिवक्ता से सलाह लें। बैंक का दावा खरीदार पर भी असर डाल सकता है; विक्रेता से ऋण चुकवाकर मुक्त होने का कागज़ लेना ही सामान्य समाधान है।
निष्कर्ष: बयाना देने से पहले बंधक की ऑनलाइन जाँच, मूल केवाला, निबंधन कार्यालय का रिकॉर्ड और बैंक NOC — ये चार काम ज़रूर करें। दस मिनट की जाँच आपको सालों के मुकदमे से बचा सकती है।
One of the most common frauds on land buyers is selling mortgaged land. The seller has borrowed against it, the original deed sits with the bank, and the buyer only finds out when a recovery notice arrives. The good news: in Bihar much of this check can be done online and free. This guide covers every way to check for a mortgage.
What a mortgage means
When someone pledges land as security for a bank or NBFC loan, the land is mortgaged. The lender holds a charge on it until the loan is repaid, and can even auction it — so check before registry.
Way 1: Bihar Bhumi’s online mortgage search
- Open the page: Bihar Bhumi’s “encumbered land search” (button below).
- Choose location: district, circle and mauza.
- Enter khata-khesra of the land you plan to buy.
- Read the result: a recorded mortgage shows the bank/institution, date and status.
Check mortgaged land ↗ On the dashboard
Not every mortgage necessarily appears in this list, so use the other methods below too.
Way 2: See the original deed
Banks usually keep the original title deed when lending. Ask the seller to show the original. Only photocopies, or a story about the original being “lost”, is a red flag.
Way 3: Encumbrance details at the registry office
Registered mortgage deeds are part of registry-office records. The office that registers the land can provide details of documents registered against the property over past years. For big deals, get this done through an advocate.
Way 4: Bank no-dues / release certificate
If the seller says a past loan has been repaid, take the bank’s no-dues certificate and the mortgage release document, and confirm with the branch if needed.
Way 5: Central registry (CERSAI) search
Banks register security interests on property with the central registry, CERSAI, which offers a public search. It is less useful for rural farmland but helpful for urban plots and flats.
Red flags
- The seller won’t show originals or is in a hurry.
- The price is far below market.
- The jamabandi remarks mention a bank or loan.
- Neighbours say there is a loan or a bank notice came.
Check these too
Along with the mortgage, check the jamabandi, khatiyan, map, pending mutations and court cases — the full list is in our 10 checks before buying guide.
FAQs
Can land with a Kisan Credit Card loan be sold?
A KCC loan can also create a bank charge on land. Before selling, the loan should be repaid and a release obtained from the bank.
What if I already bought mortgaged land?
See an advocate at once. The bank’s claim can affect the buyer; the usual fix is getting the seller to repay and obtain a release.
Bottom line: before paying an advance, do the online mortgage search, see the original deed, check registry records and get a bank NOC. Ten minutes of checking can save years of litigation.